Tim Cook's Farewell Earnings Call Lands in the Middle of Apple's Biggest Test Yet
The company hit a $5 trillion valuation the same week it's grappling with a memory shortage, looming price hikes, and an AI strategy that still lags the competition.
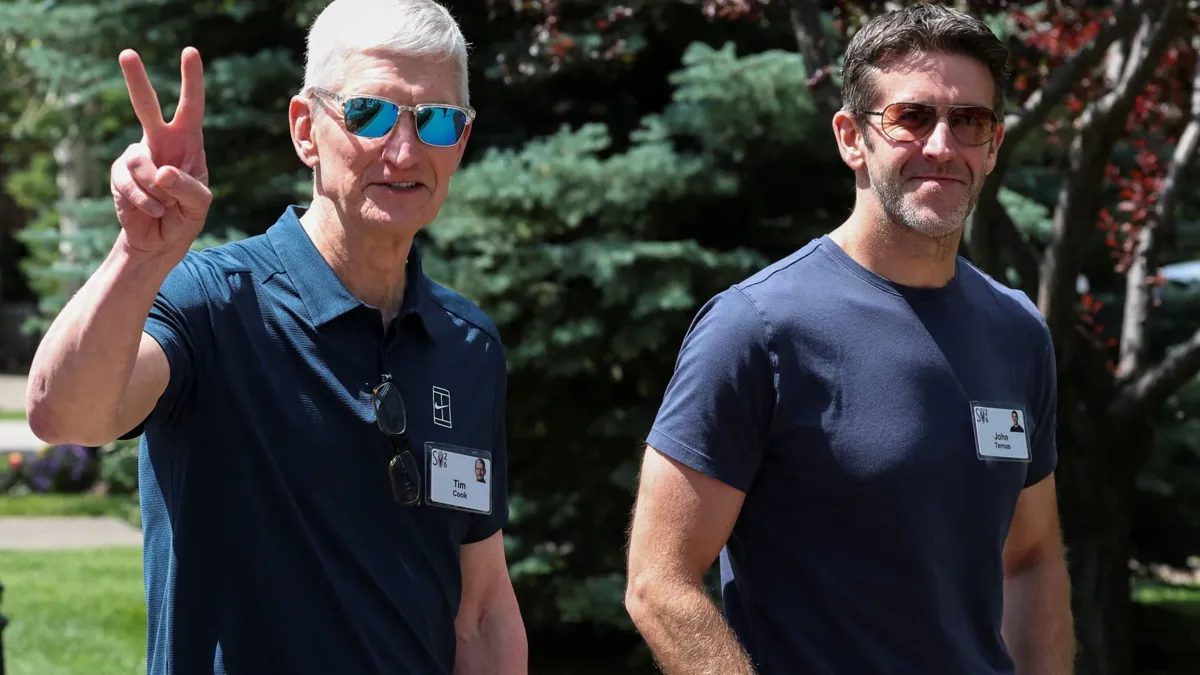
Tim Cook will host his last earnings call as Apple's CEO on Thursday, and the timing could hardly be more loaded. Just days earlier, Apple's stock touched a $5 trillion market cap, pushing past Nvidia to become the world's most valuable company. The shares are up 25% this year, outpacing every other megacap. By any normal measure, this would be a moment for Apple to take a lap.
Instead, the company is dealing with a memory chip shortage squeezing its supply chain, a scramble for manufacturing capacity, and price hikes on some of its most important products. And it's still trying to convince the world it hasn't fallen behind on AI.
Cook steps down on September 1 and moves into the role of executive chairman. His successor is John Ternus, a 25-year Apple veteran who currently runs hardware engineering. Ternus said relatively little on the company's April earnings call, which came shortly after the leadership transition was announced. Thursday will likely be different. Investors will want to hear directly from the man who's about to become just the second Apple CEO since Steve Jobs stepped down in 2011, months before his death.
Cook's 15 years at the helm produced a roughly fourteen-fold increase in Apple's valuation, an extraordinary run by any standard. But it also came without a major new hardware category to follow the iPhone, and with a costly, still-unproven bet on the Vision Pro headset, which launched in 2024 and has yet to find a mass audience.
"Tim Cook, he's a really talented supply chain operations guy, and I think he's just done just a remarkable job of navigating the environment," said Melissa Otto, head of Visible Alpha research at S&P Global. She expects the call to offer some clarity on how Apple plans to manage its current set of problems.
A memory crunch hits right before the big quarter
The most immediate issue is chips. Citing the global memory shortage, Apple raised starting prices on iPads and Macs last month by at least $100, with some configurations jumping more than $1,000. Analysts widely expect iPhone price increases to follow later this year. In a separate move, Apple this week rolled out a partnership with buy-now-pay-later provider Klarna, letting U.S. customers lease an iPhone for up to two years starting at $17.99 a month, a signal the company is thinking about how to soften the blow of higher prices for everyday buyers.
Those broader price increases, some as steep as 20% on certain devices, were announced right at the end of the fiscal quarter Apple is about to report, so they haven't shown up in the numbers yet. Analysts expect revenue for the quarter ended in June to be up about 16% year over year, with growth cooling to around 12% in the current quarter. The real question for investors isn't this report. It's what happens to demand once higher prices hit the December quarter, historically Apple's biggest.
The pressure isn't unique to Apple, but it may hit rivals harder. Counterpoint Research projects global smartphone shipments will fall nearly 14% this year, the sharpest drop since 2013, with the low end of the market, largely Android devices, most exposed because those manufacturers have less room to absorb rising memory costs. Goldman Sachs analysts, who rate Apple a buy, wrote this week that the company could actually gain market share as competitors raise prices too.
Apple itself hasn't changed its iPhone sales forecasts since warning about the memory situation in June, though some analysts are adjusting their models anyway. A few even argue the price hikes could be good for the bottom line. "We continue to believe that Apple fundamentals are very strong, with myriad price hikes likely to drive upside to revenue and EPS over the next 6-18 months," Morgan Stanley analysts wrote last week, while still trimming their Mac sales forecast for the September quarter by 8% due to supply constraints.
The bigger problem is AI
The chip shortage is a near-term headache. The longer-term risk is Apple's position in AI, where it has taken a fundamentally different path than its megacap peers. Rather than pouring tens of billions into building or training its own advanced models, Apple is licensing AI technology from Google and using Google's cloud infrastructure. The gap in spending is stark: while hyperscalers are collectively spending well over $100 billion on capital expenditures this year, with some set to top $200 billion, Apple is expected to spend just over $11 billion, including $3.4 billion in the most recent quarter, according to FactSet.
That restraint drew criticism early on, but sentiment is shifting. "While Apple was initially bruised by many investors for not joining the LLM investment cycle, investors are coming around to Apple's industry-leading" free cash flow, Baird analysts wrote this month, recommending the stock.
Before turning to Google, Apple's primary AI partner was OpenAI, whose ChatGPT technology was woven into Siri and other parts of iOS. That relationship has largely unraveled. Apple sued OpenAI on July 10, alleging trade secret theft; OpenAI has denied the allegation.
That leaves Apple's redesigned Siri, released in beta in June and expected to launch fully this fall alongside new iPhones, as the company's most visible proof point that it can still compete on AI. It needs the relaunch to land well with consumers and needs a steady stream of follow-up features to keep pace with an industry moving, as the competitive landscape suggests, faster than Apple has moved in years.
A hint of a strategy shift under Ternus
There are early signs Apple could get more aggressive on AI investment once Ternus takes over. Under Cook, Apple generated so much free cash that it bought back more than $1 trillion in its own stock. But in its last earnings report, the company quietly altered a cash policy it had held since 2018, when it aimed to become "net cash neutral" by matching cash on hand to total debt. Now Apple says it will evaluate cash and debt independently, a change that could give it more flexibility to spend on AI rather than shareholder returns.
"We invest in the business first and foremost and then look to kind of return excess cash to shareholders," Apple CFO Kevan Parekh said on the April call.
Thursday's report will be the last Cook delivers as CEO, but the questions investors ask won't really be about him. They'll be about whether Ternus, stepping into the job at a record stock price and a genuinely uncertain moment for the company's supply chain and AI ambitions, is ready to chart Apple's next move.


